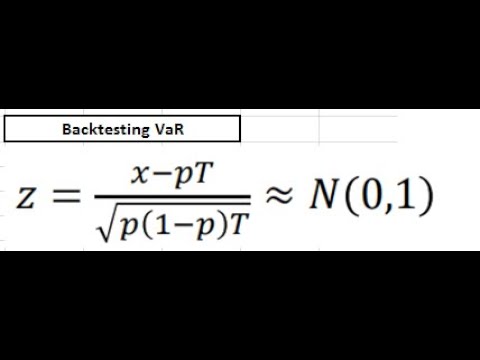Showing 120 of 120on this page. Filters & sort apply to loaded results; URL updates for sharing.120 of 120 on this page
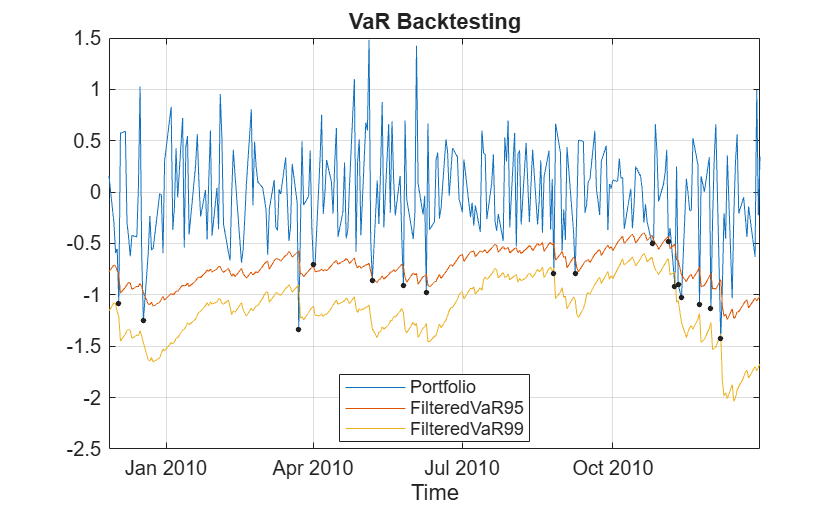
VaR Backtesting Workflow - MATLAB & Simulink
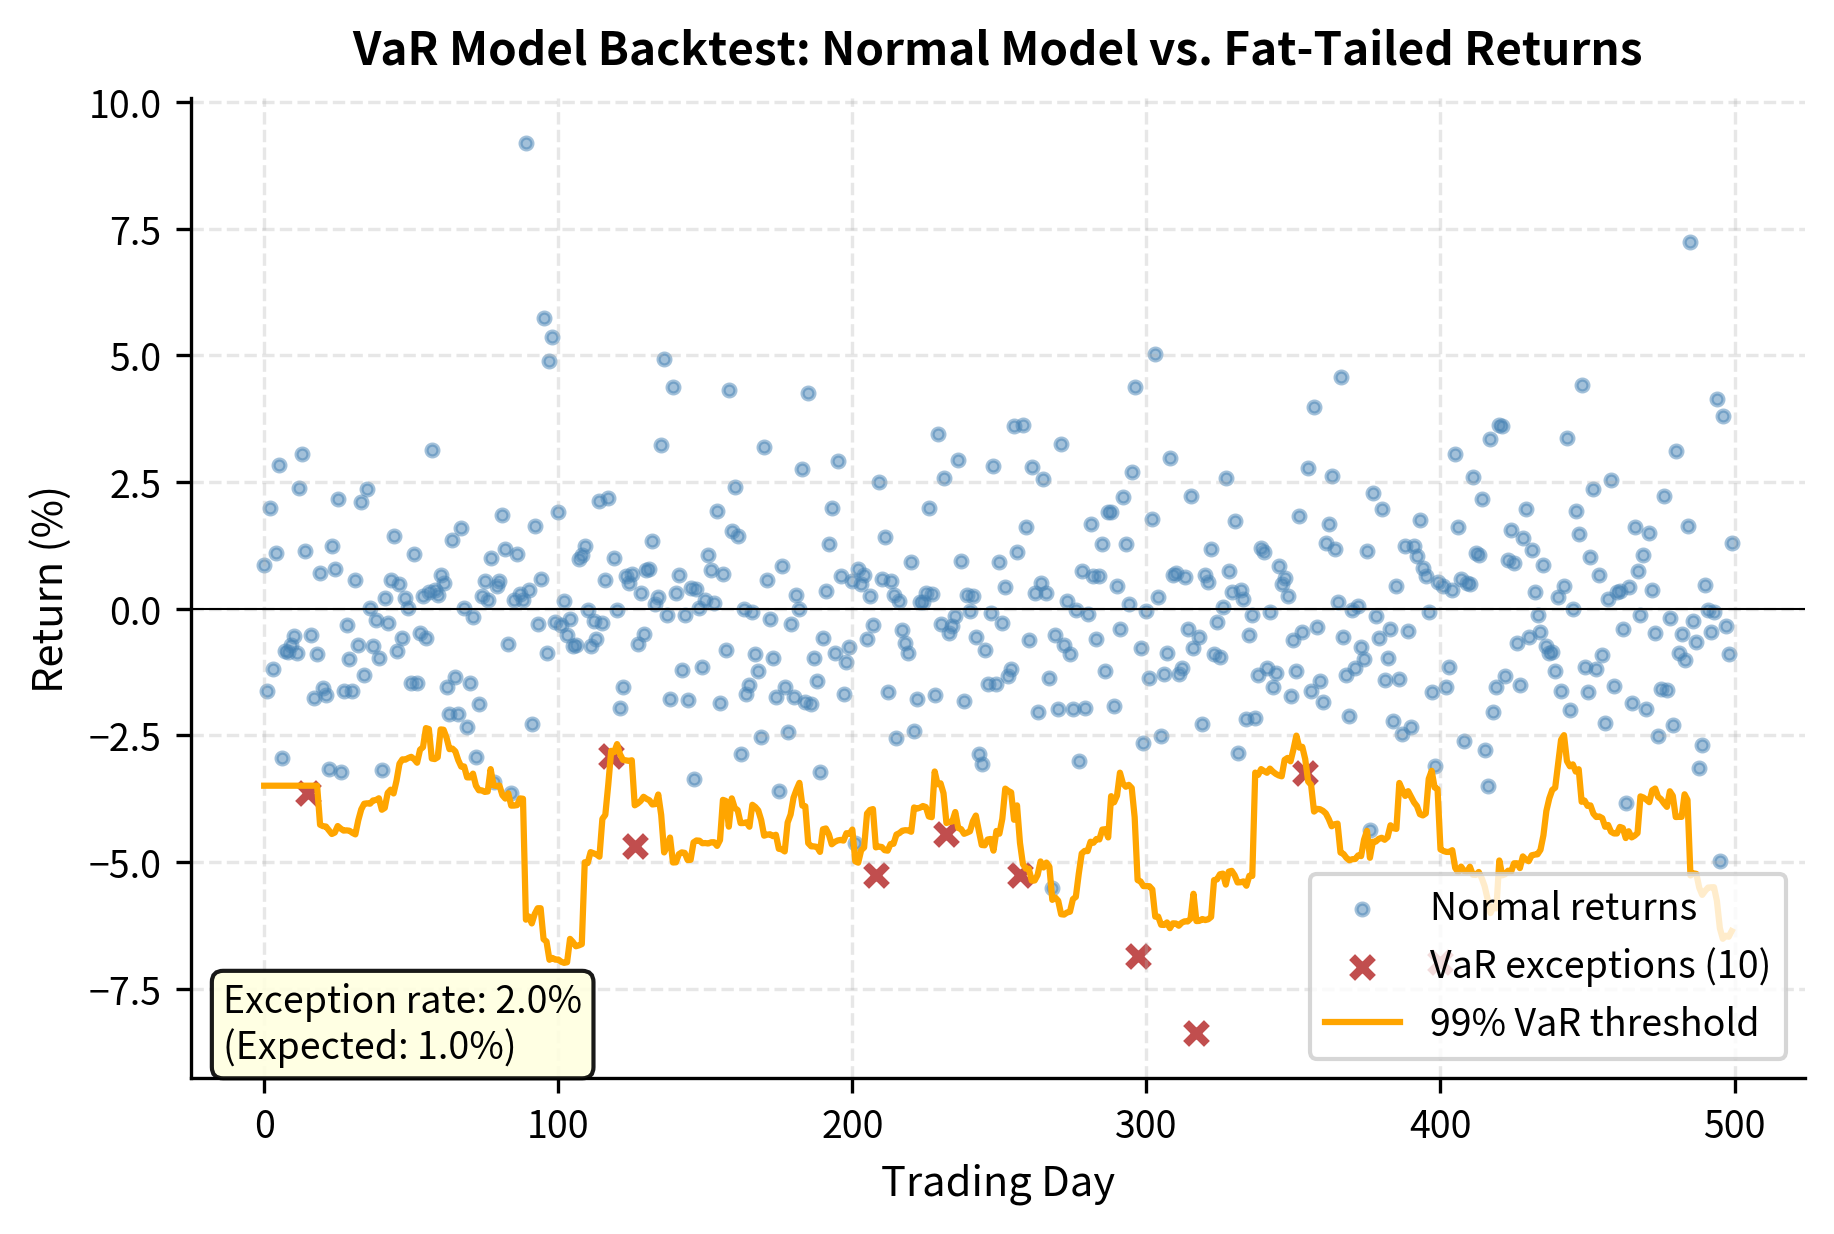
6: Combined figure of the VaR backtesting with different fat-tailed ...
Built Excel VaR Project with Backtesting for AAPL, GLD, BTC | VAIBHAV ...
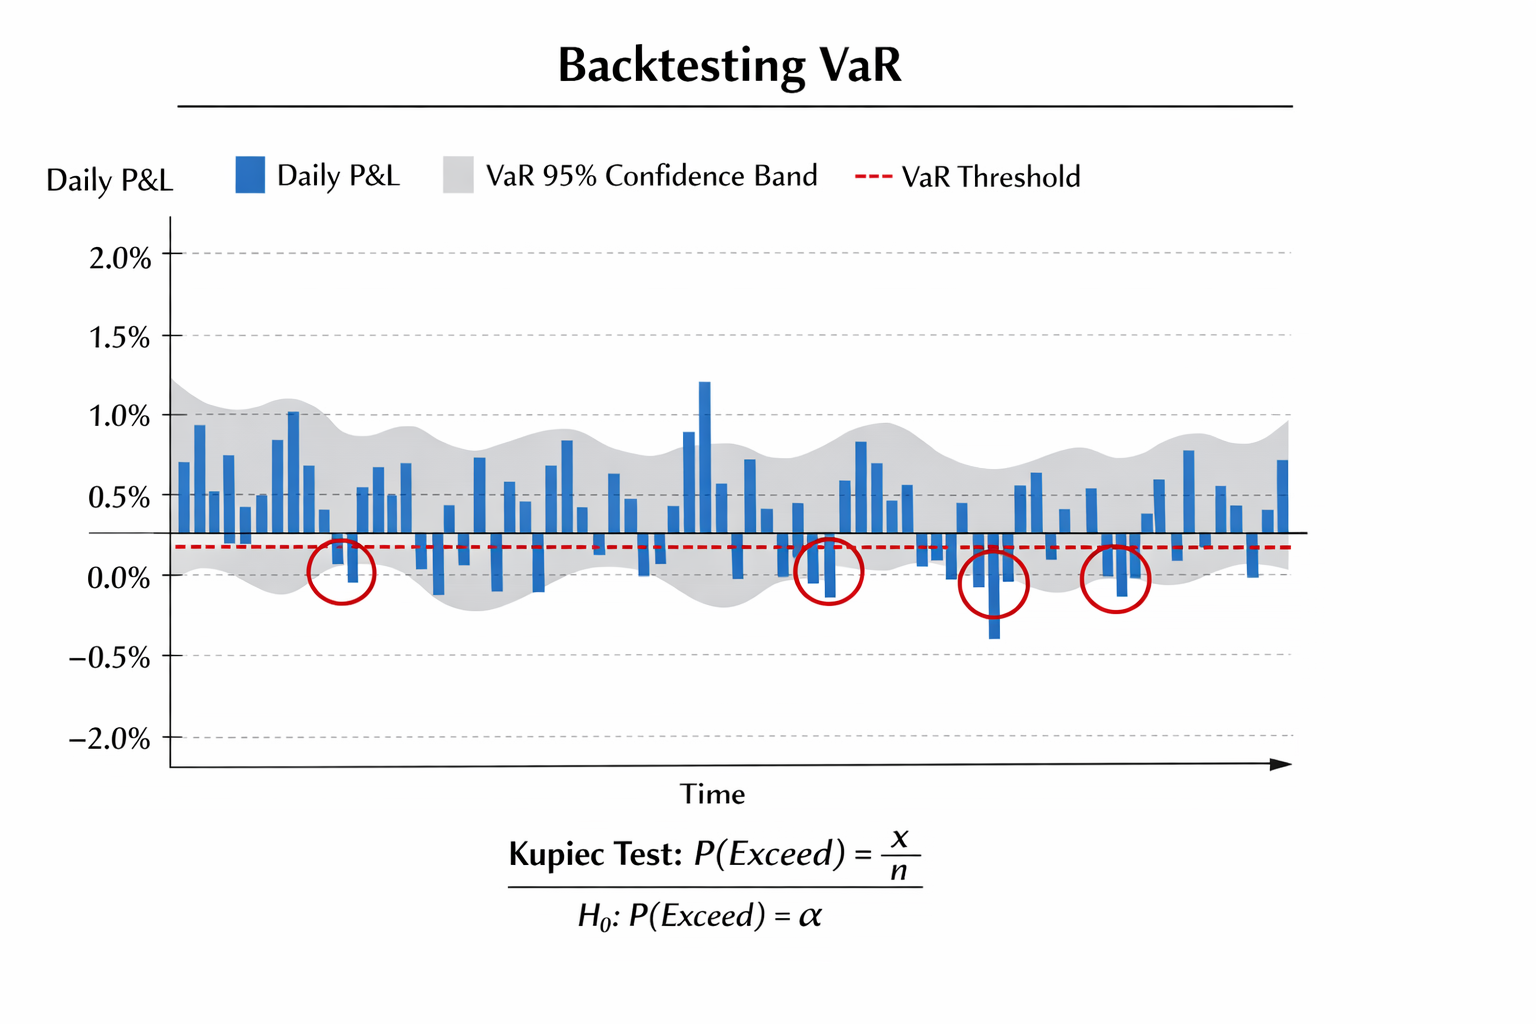
VaR Backtesting Calculator | Kupiec POF Test & Basel Traffic Light ...
Forecasting and Backtesting of VaR in International Dry Bulk Shipping ...
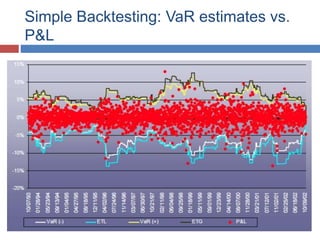
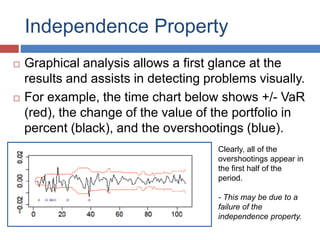
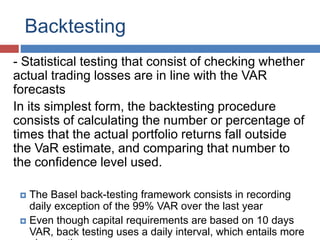
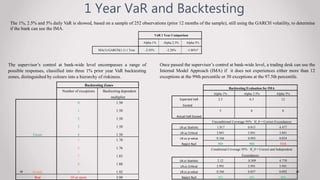
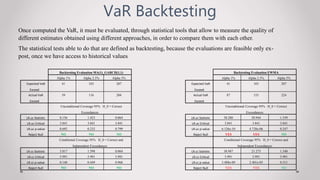
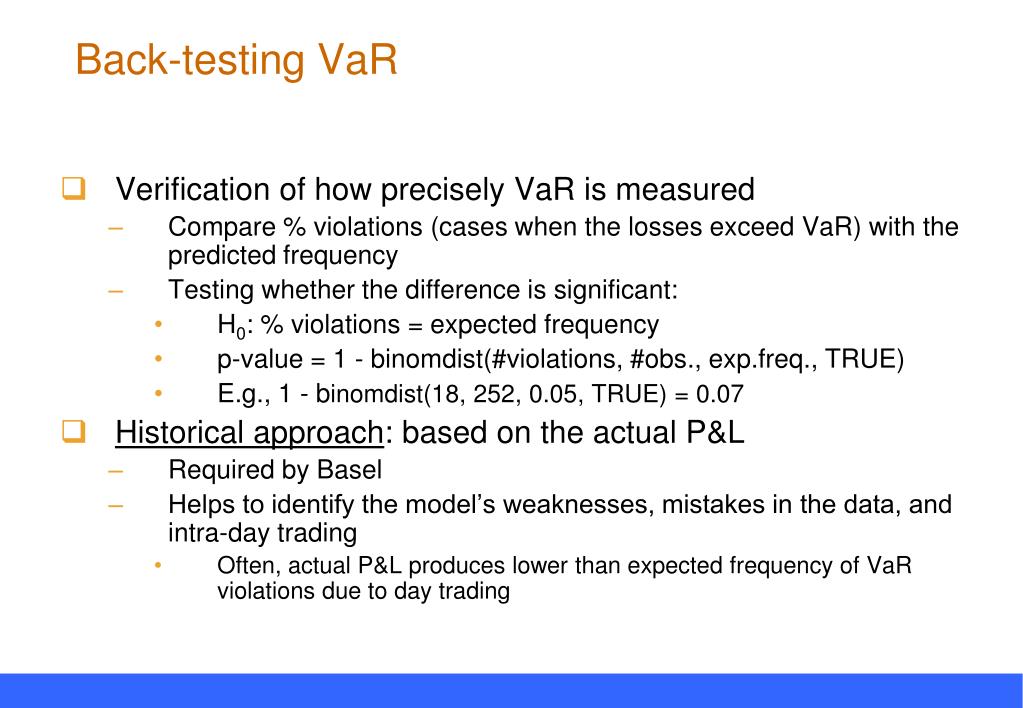
Backtesting var | PPTX
VaR Backtesting in Turbulent Market Conditions : Enhancing the ...
Backtesting VaR analysis for benchmark models. Volume weighted market ...
Backtesting based on loss function for VaR i 5% . Panel A reports the ...
Backtesting Var Model – A Review of Backtesting and Backtesting ...
Var Backtesting , BacktestVaR : Backtest Value at Risk (VaR) – EXAIP
VaR backtesting statistics at 95% confidence interval | Download ...
VaR Backtesting Calculator Excel Template - Free Download - All For One
Backtesting VaR (Value at Risk) - YouTube
Backtesting VaR estimation under normal distribution. | Download ...
Backtesting VaR Models in Real Markets | The Risk Insider posted on the ...
21): Backtesting VaR graph for EVT-GARCH (full line), EVT (dashed line ...
Backtesting Tests of 5% VaR Forecasts for Nasdaq Index VaR Forecasting ...
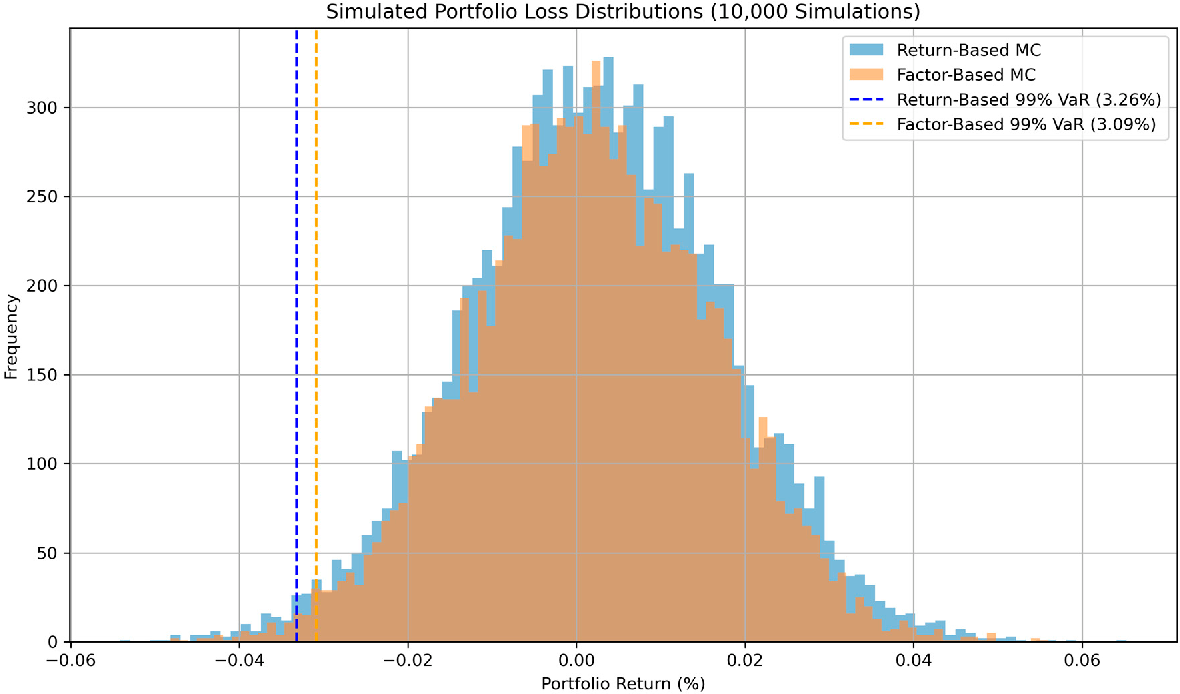
Monte Carlo-Based VaR Estimation and Backtesting Under Basel III
US dealers recorded 15 VAR backtesting exceptions in Q4 2024… | Risk.net
VaR Backtesting for gold return | Download Scientific Diagram
Backtesting of VaR forecasts at 95% confidence level. | Download ...
Power of a VaR BackTest (FRM Part 2, Book 1, Market Risk, Backtesting ...
Backtesting VaR | Risk Management Atlas
Backtesting VaR Thresholds for One-Step-Ahead Forecasts. | Download Table
Backtesting VaR Thresholds | Download Table
Backtesting VaR and CVaR estimates of FTSE100 at level 1%. All the risk ...
GMM-Based Backtesting for VaR | PDF | Value At Risk | Hypothesis
Understanding VaR and Backtesting in Risk Management | Course Hero
P2.T5. Lecture 3: Backtesting VaR Models and Error Analysis - Studocu
Backtesting VaR Delta-Normal — Cursos documentation
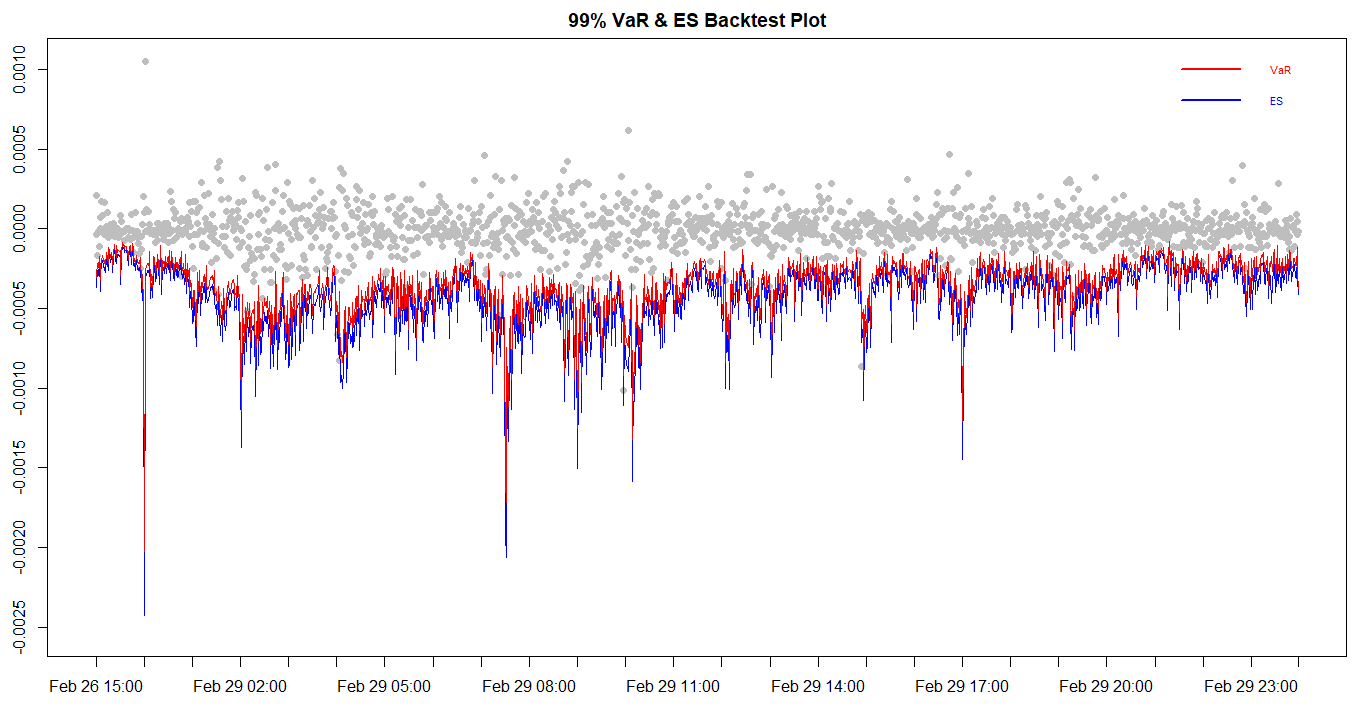
Backtesting Results of VaR and ES | Download Scientific Diagram
Results of VaR backtesting (% violation) of conventional and modified ...
Gráficos de Backtesting para el VaR a 10 días de los TES por ...
Backtesting VaR estimation under EWMA model. | Download Scientific Diagram
Figure 1 from Monte Carlo-Based VaR Estimation and Backtesting Under ...
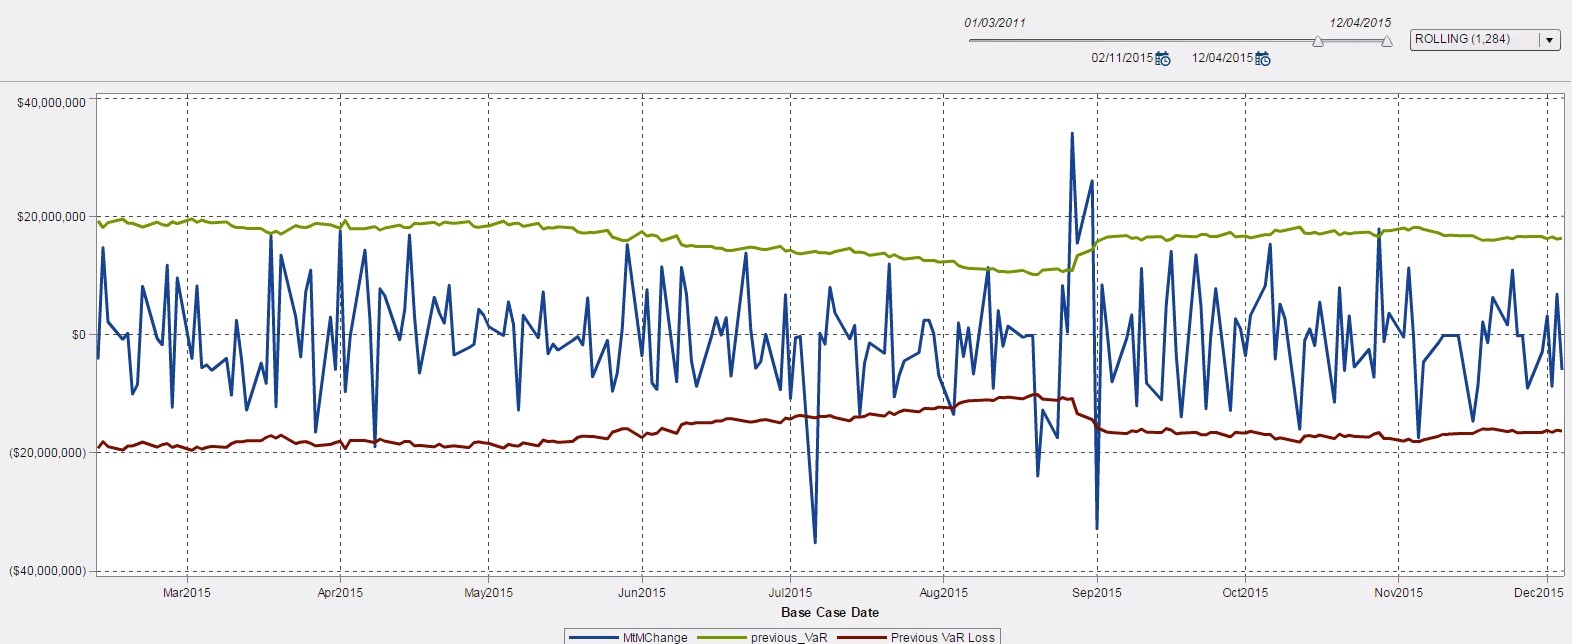
VirtualOil portfolio benchmarking and VaR backtesting - SAS Voices
Value-at-Risk Estimation and Backtesting - MATLAB & Simulink Example
Estimate VaR for Equity Portfolio Using Parametric Methods - MATLAB ...
Liquidity Risk Management: Beyond VaR and Market Risk - Interactive ...
VaR and ES for Whole Sample Period | Download Scientific Diagram
Backtesting VaR: How to Validate Your Risk Model | Ryan OConnell, CFA
Backtesting - MATLAB & Simulink
Backtesting
Backtesting historical VaR: out of sample testing - YouTube
Backtesting Var: Learning Objectives | PDF
GitHub - riskarcane/var-calculator: Comprehensive VaR calculator with ...
Is Your VaR Model Truly Valid? | Prateek Yadav, FRM, CQF
An Analysis of Different Methods for Backtesting Value at Risk (VaR ...
1% VaR forecast backtest results. | Download Table
Saddlepoint backtest of tail risk of VaR Saddlepoint backtest of tail ...
5% VaR forecast backtest results for 2018. | Download Table
Annual Report 2023 – UBS AG - UBS Group AG
Backtesting and estimation error: value-at-risk overviolation rate ...
Schematic diagram of VaR and logarithmic returns calculated using ...
INDX VaR backtest, from 2014-02-05 to 2017-06-07 | Download Scientific ...
Backtesting Model Validation , Model Validation Techniques for Time ...
Table 1 from Backtesting value-at-risk accuracy: a simple new test ...
(PDF) Backtesting Value-at-Risk Accuracy: A New Simple Test
Kupiec Pof Test – Backtesting VaR: Kupiec coverage test (Excel) – YXYKU
Backtesting de VaR: Validación y Limitaciones | PDF | Intervalo de ...
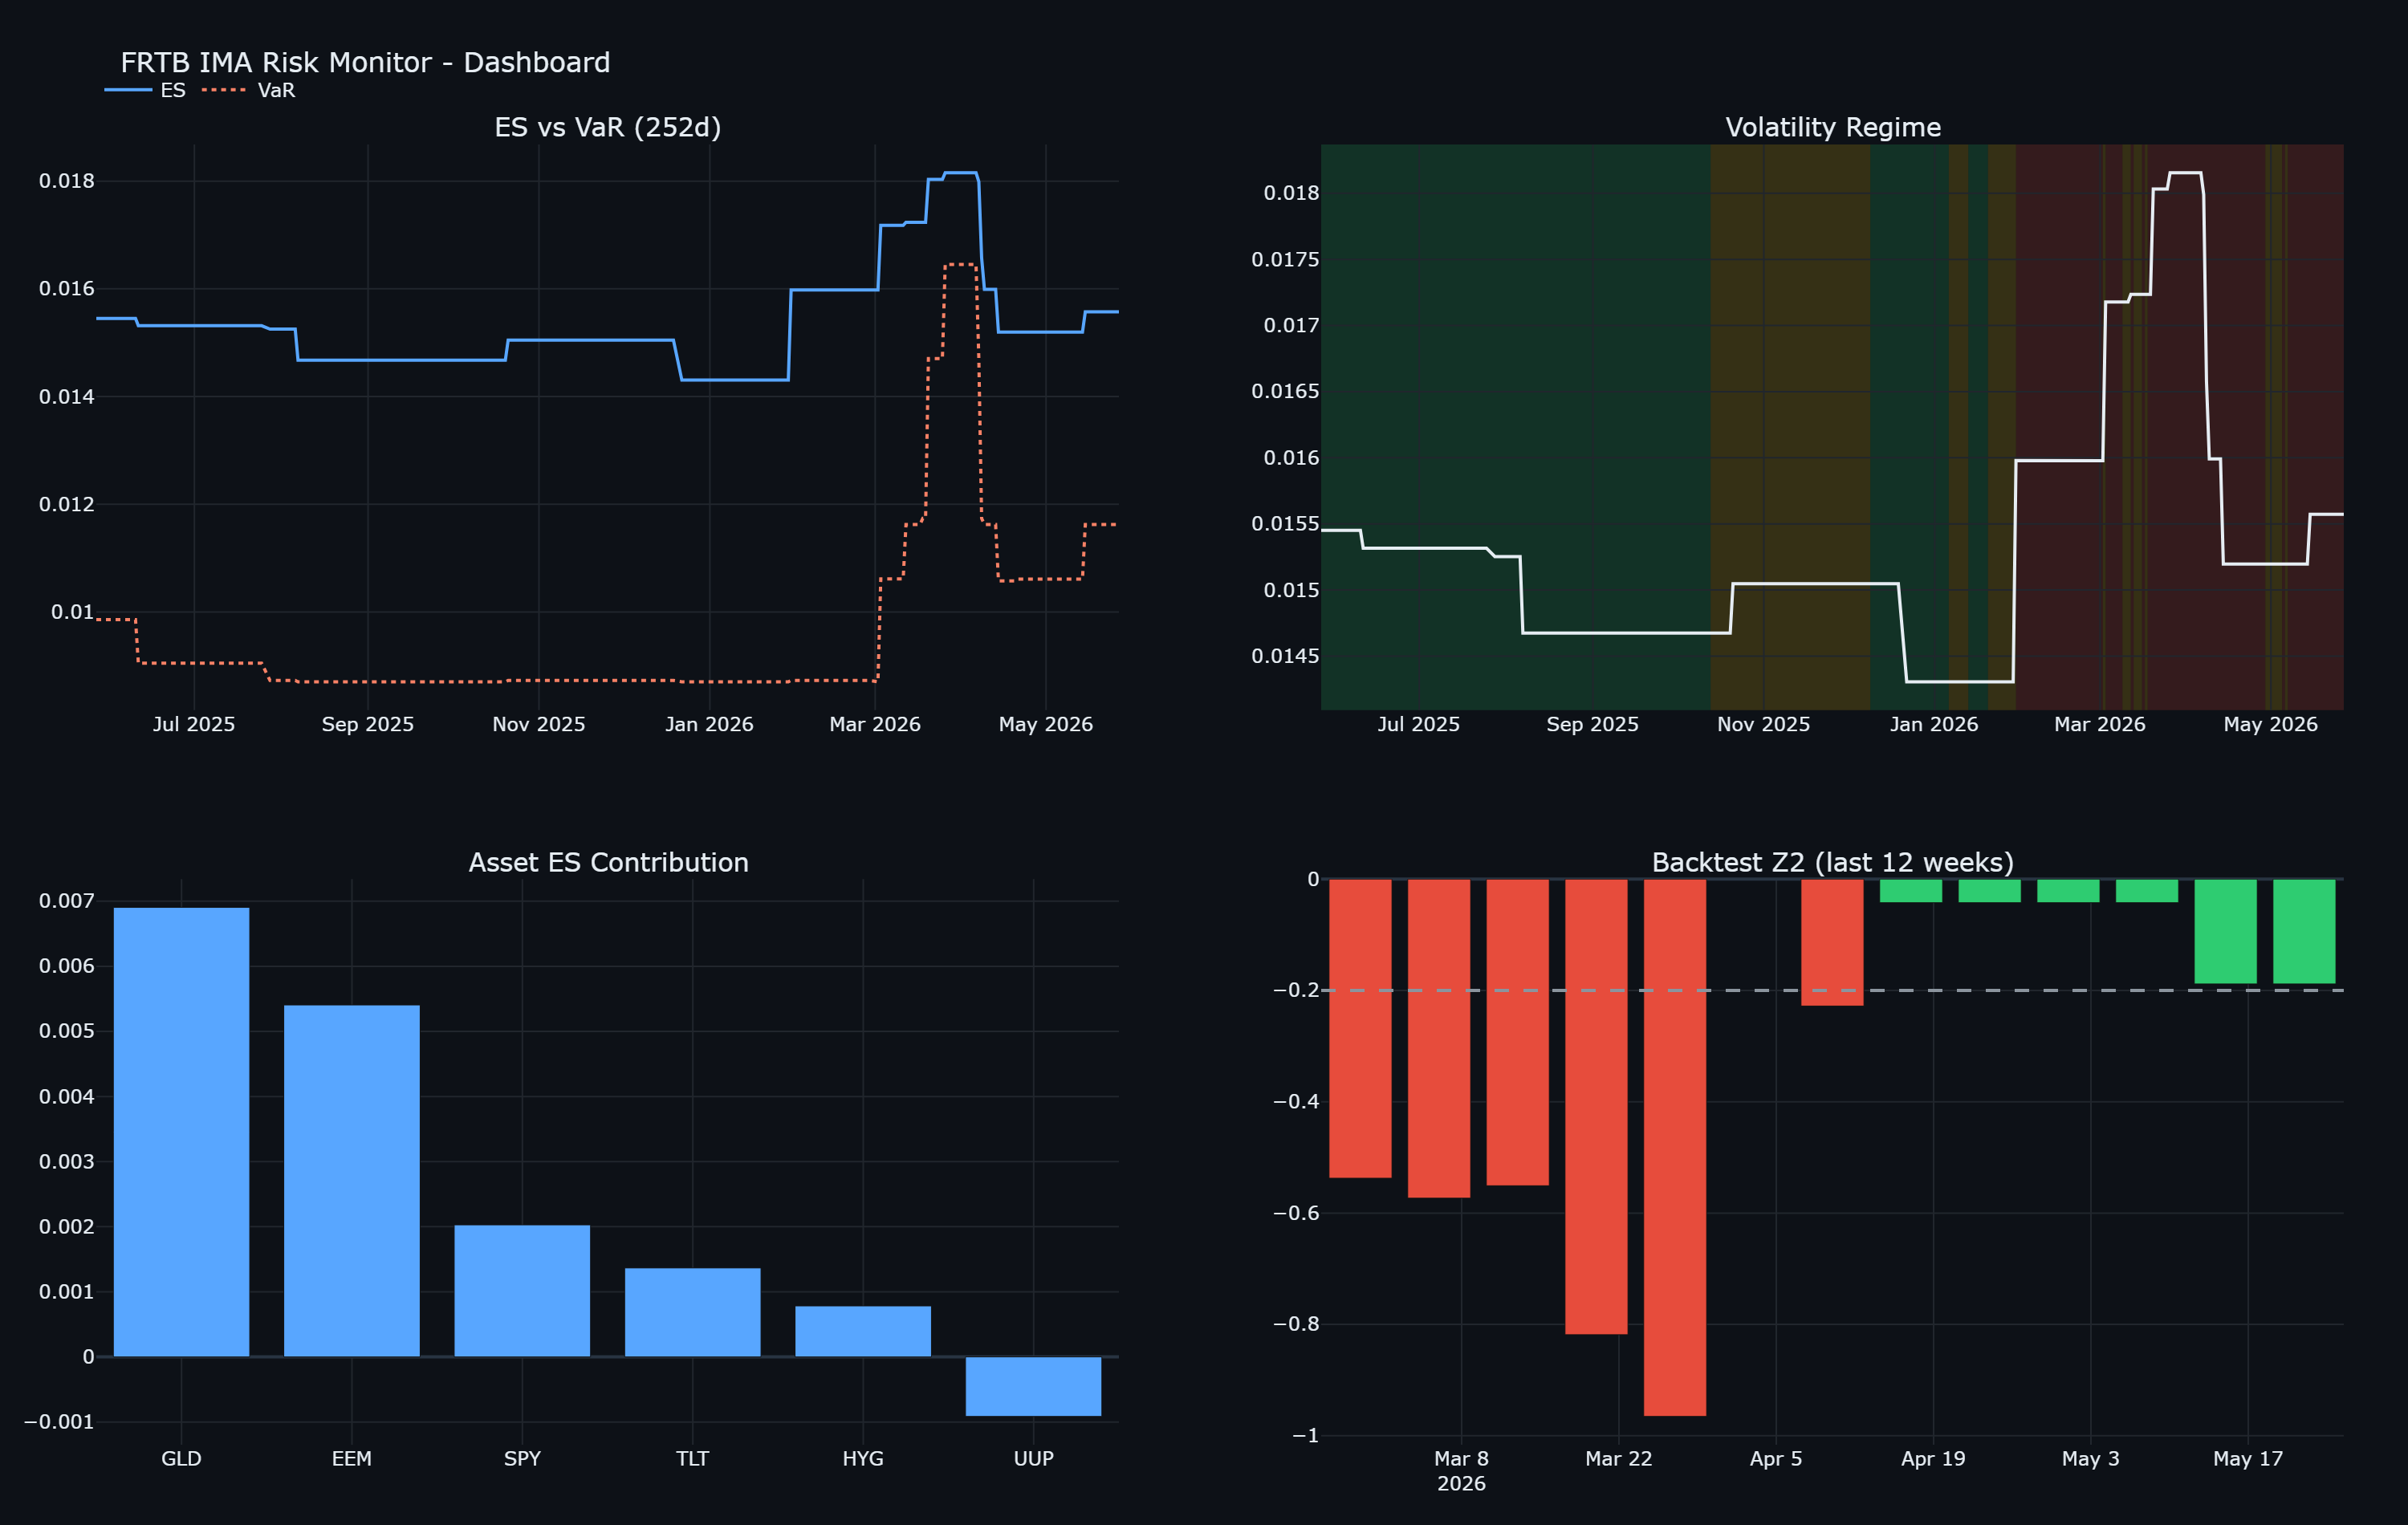
Market Risk Engine: Integrated VaR, Stress Testing, and Backtesting ...
Example: Backtesting a One-Day 95% EUR Value-at-Risk Measure
Backtesting Value at Risk (VaR) | Finance Train
Valuation Backtesting at Eugene Julian blog
Geometric-VaR Test for Risk Backtesting | PDF | Value At Risk | P Value
Manifold-BT, Python Backtesting Library with Rust Core
3.backtesting VaR | PDF
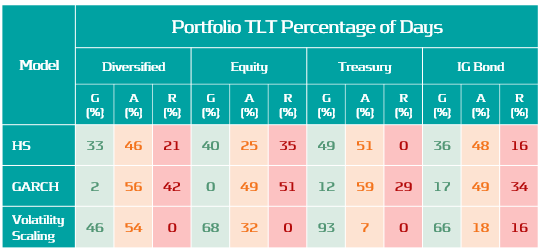
Proportion of VaR estimations classified as 'Green', 'Amber' and 'Red ...
(PDF) Value-at-risk (VAR) estimation and backtesting during COVID-19 ...
VaR backtesting: British pound (in euros) and South African rand (in ...
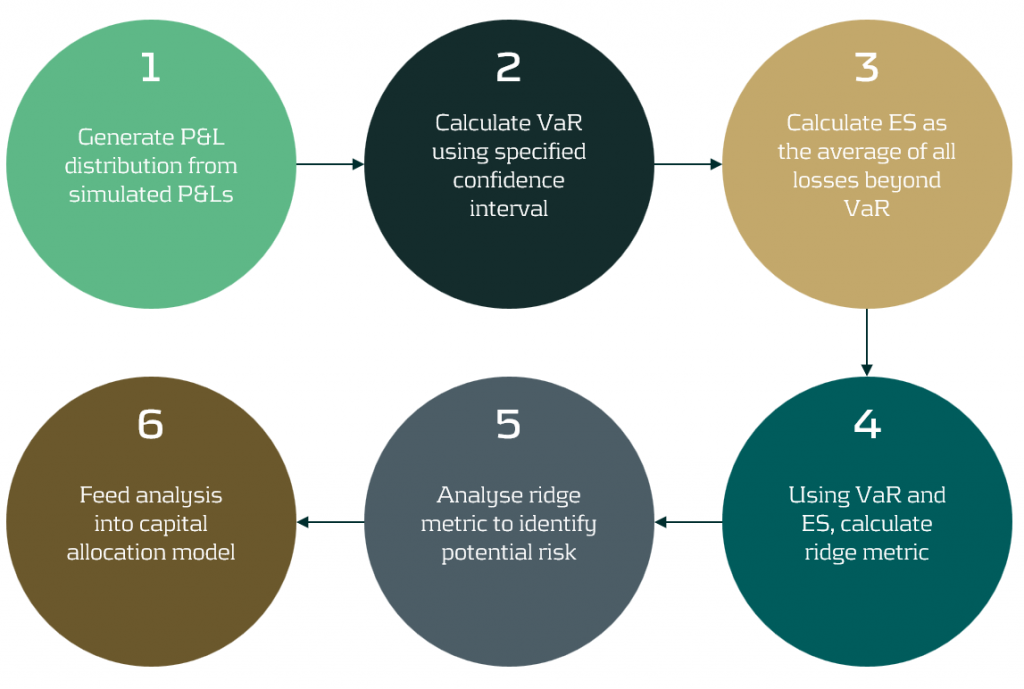
The Ridge Backtest Metric: Backtesting Expected Shortfall - Zanders
Annual Report 2024 – UBS AG - UBS AG
plot - Visualize value-at-risk (VaR) or expected shortfall (ES) and ...
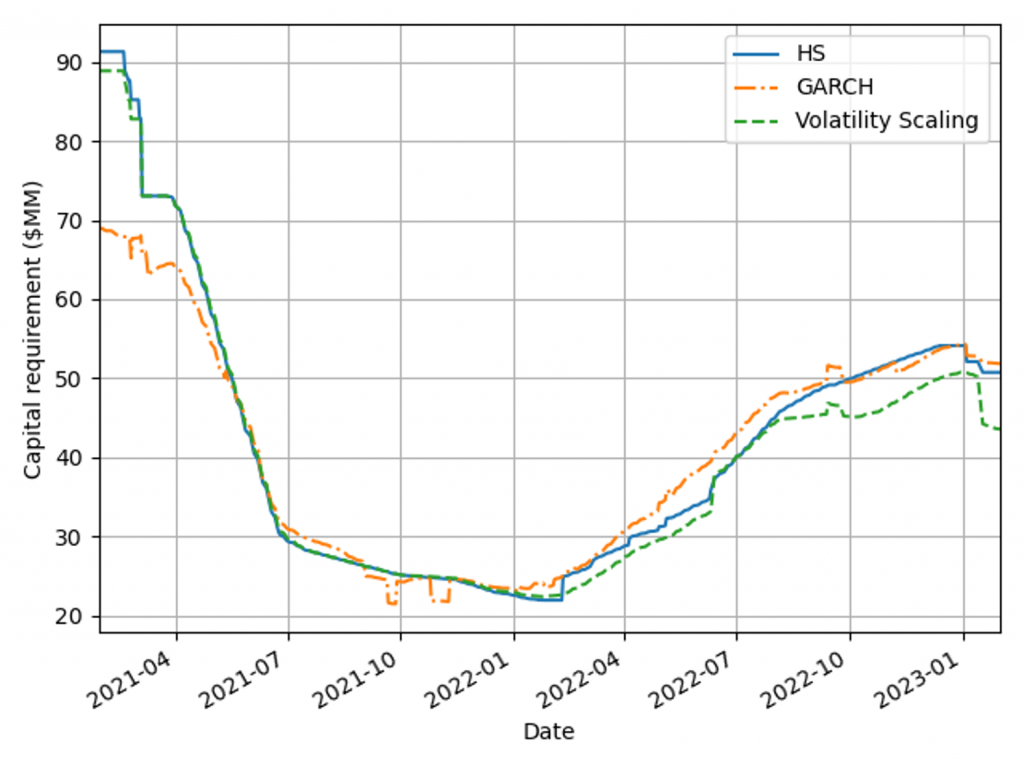
Historical Value-at-Risk Estimation with US Treasury Bonds - MATLAB ...
Presentazione tesi | PPT
Value at Risk backtesting. | Download Table
PPT - Class 2 Measuring Market Risk PowerPoint Presentation, free ...
Oil, options and inflation: Looking for a silver lining - SAS Voices
Value-at-Risk-VaR 1 zzzzzzzzzzzzzzzzzzzz | PPT
VaR-Backtesting/backtest.py at master · BayerSe/VaR-Backtesting · GitHub
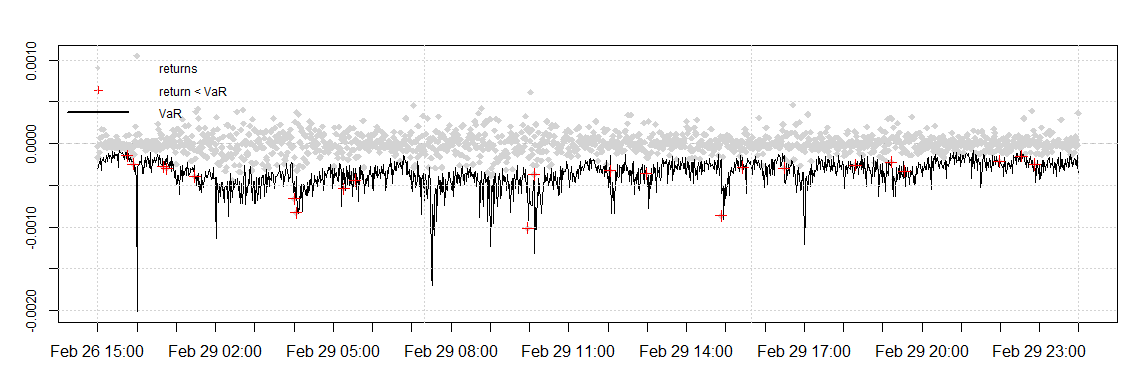
High-frequency analysis, Model Validation and Intraday risk metrics ...
#riskmanagement #var #risk #riskmitigation #riskanalysis # ...
GitHub - ibaris/VaR: Value at Risk and Backtest Routines · GitHub
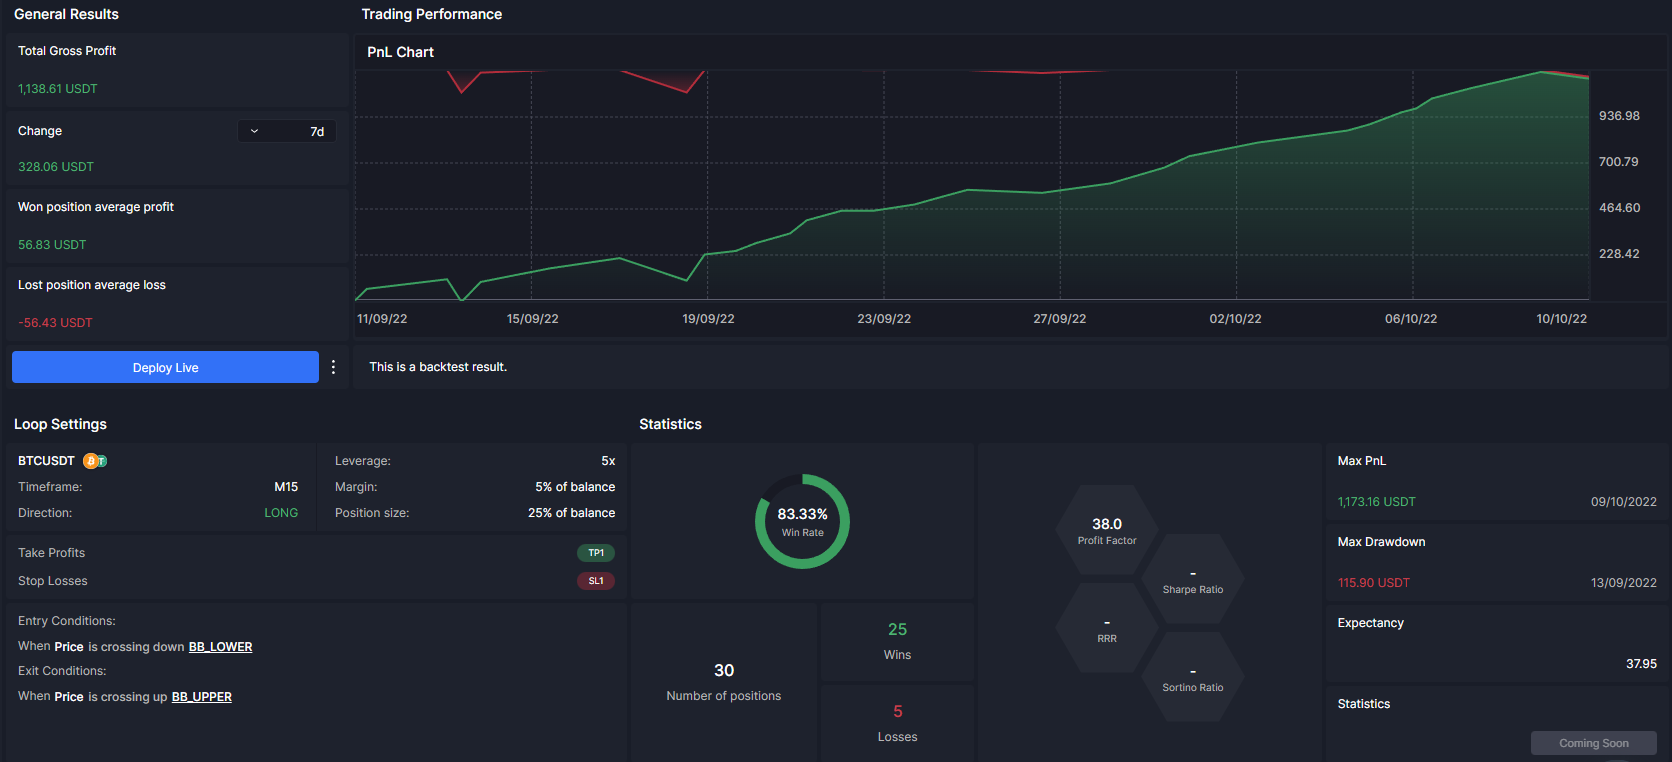
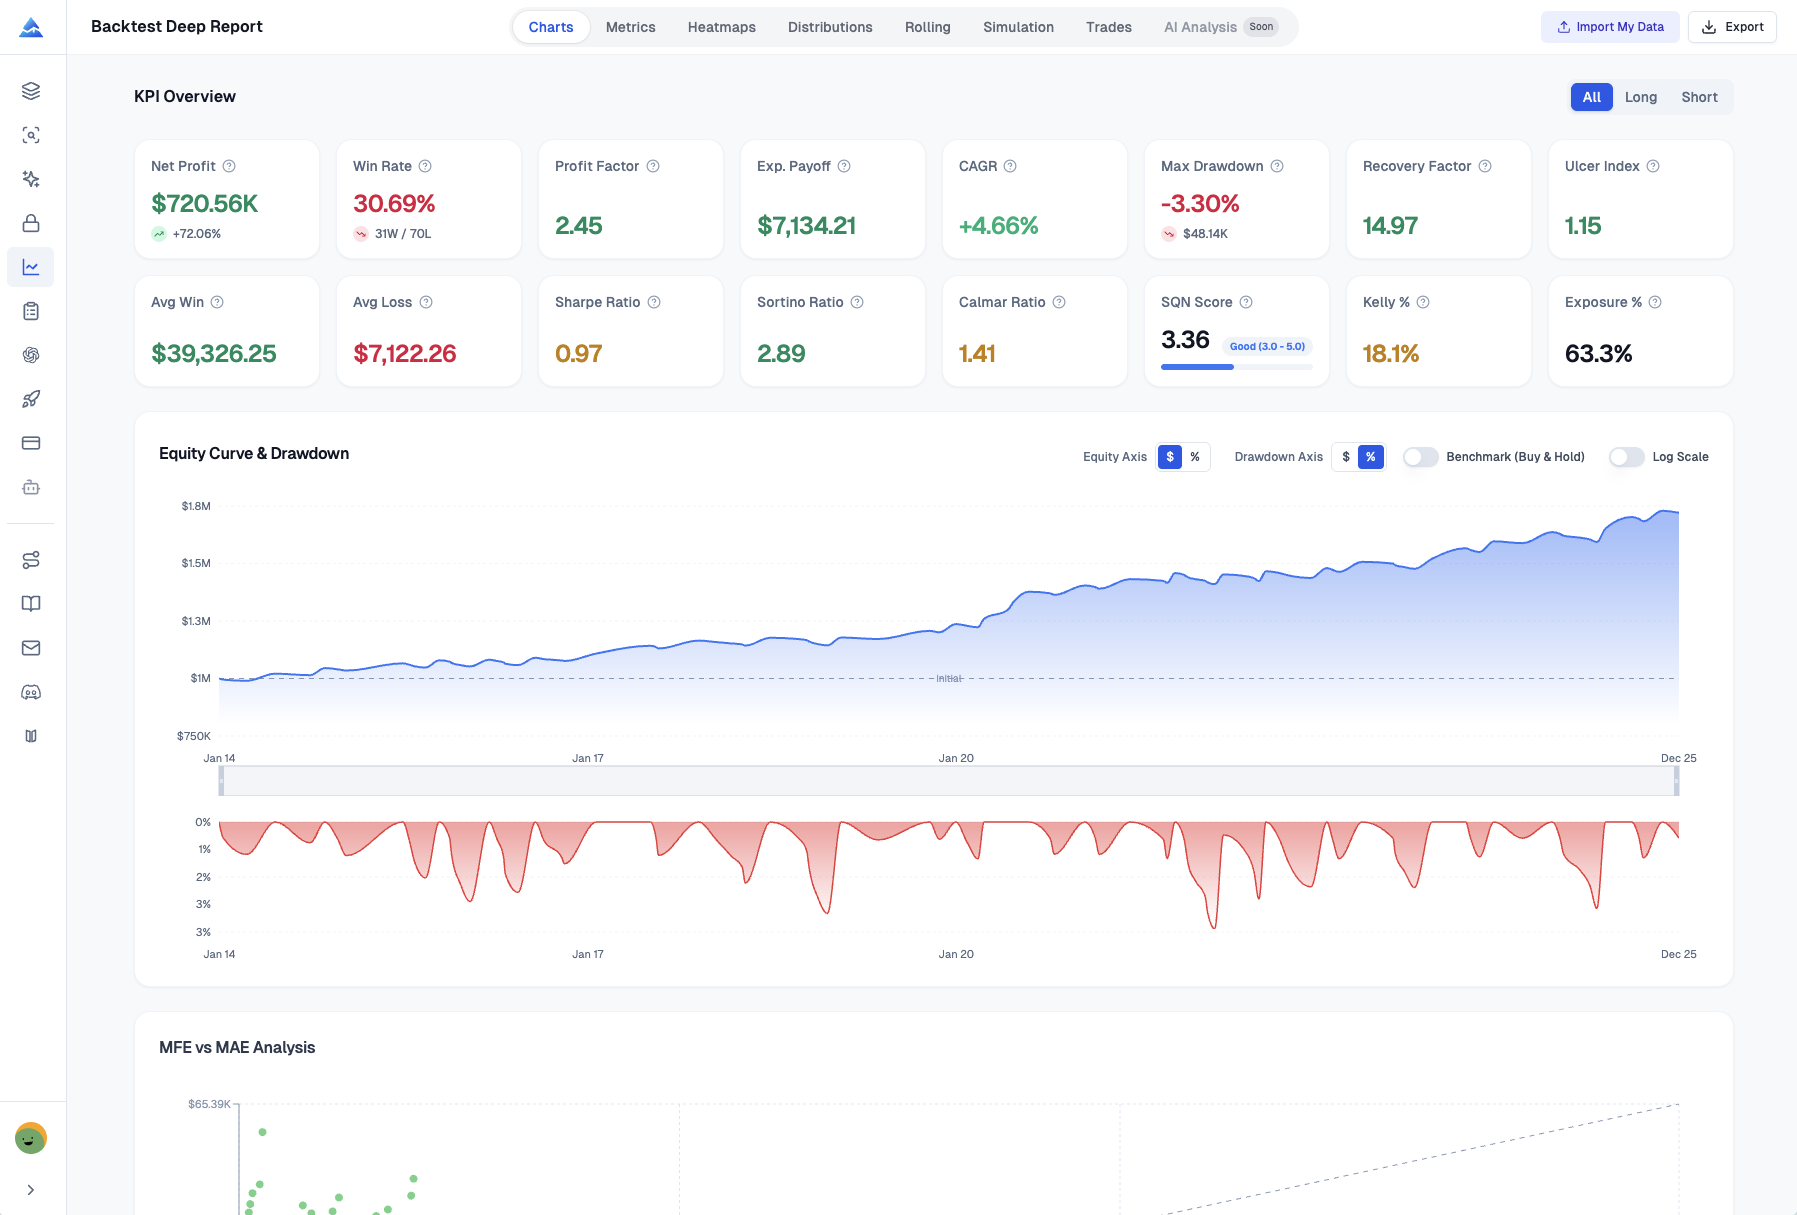
TradingView Backtest Report: Advanced Strategy Analysis | Pineify
Sequential quantile estimation (VaR backtest) of a long position in ...
Resources | Lodestar Risk Management
Assessment of the dynamic properties of the joint distribution-VaR ...
PPT - Value-at-Risk (VaR) PowerPoint Presentation, free download - ID ...
Marks Guo | Statistics & Finance
Falando um pouco mais sobre o Backtest do Value-at-Risk (VaR) X Teste ...
Measuring and Managing Market Risk | PDF
PastPaperHero | Backtesting, stress testing, and risk attribution ...
Chapter 9 Market Risk | R Notes for QRM
GitHub - felipeOL10/VaR-CVaR-and-VaR-backtesting · GitHub